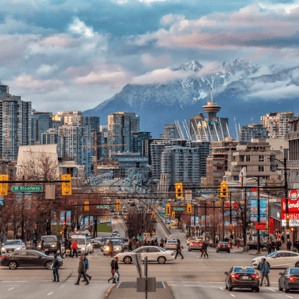
Owning a home in Canada has become harder to afford. According to the Canadian Real Estate Association (CREA), the average house price in Canada hit $666,538 in September 2026. High prices and interest rates have squeezed buyers across the country. Where you live makes a huge difference. A home in Vancouver can cost far more than the national figure, while smaller cities in Atlantic Canada are much cheaper.
Below, you'll find national, provincial and city prices, what a typical mortgage payment looks like, land transfer tax in each province, and how renting compares with buying. If you're close to buying, learning how to shop for a mortgage will help you set a budget you can stick to.
Key Points
- Canada's average home price was $666,538 in September 2026, a 1.6% drop over twelve months.
- Region matters most. British Columbia averages $923,887 and Ontario $791,691, while New Brunswick is the cheapest province, with a $341,700 benchmark.
- Prices are climbing in Alberta, Quebec, Manitoba, Saskatchewan and most of Atlantic Canada, and slipping in British Columbia, Ontario and Nova Scotia.
- At the national average price, a mortgage costs about $3,100 to $3,800 a month, with the low end for buyers who put 20% down.
- The "average" is a mean, so a few luxury sales can drag it up. The median, which reflects a typical home, is often lower.
Average House Price In Canada: Where Things Stand In 2026
In September 2026, homes across Canada averaged $666,538. That was 1.6% less than in September 2025.1 Treat that as a starting point only. Prices change sharply from province to province, from city to city and between types of homes, so what you pay could be far above or below it.
CREA's national MLS HPI benchmark measures a typical home instead of whatever mix of homes sold. It sat at $651,400 in September 2026, down 3.4% on the year.1 That's 22.5% under the March 2022 high of $840,400, and about 2.8 times the January 2005 level of $233,200.
Canada Benchmark Home Price, 2005 To 2026
Peak $840,400 in March 2022 | September 2026: $651,400
Source: CREA MLS Home Price Index, Canada composite benchmark price, not seasonally adjusted.
How Have Canadian Home Prices Changed Over Time?
Over the long run, prices have climbed a lot, with some big swings along the way. The chart shows the national benchmark hitting $840,400 in March 2022 before easing to $651,400 by September 2026. Even so, that's around 2.8 times the January 2005 figure of $233,200.1
What Happened In The Last 12 Months?
CREA data shows the national average slipped 1.6% in the year ending September 2026.1 The regional split matters more. Alberta, Quebec, Manitoba, Saskatchewan, New Brunswick, Prince Edward Island and Newfoundland and Labrador all gained, while British Columbia, Ontario and Nova Scotia lost ground.
Why Is The Median Price Often Lower Than The Average?
Because the average is easy to skew. A headline "average house price" is usually the mean, which is every sale added together and divided by the number of sales. A handful of very expensive homes, common in Vancouver and Toronto, can push that number up.
The median is simply the middle sale. Half of homes sold for more and half for less. Luxury sales barely move it, so it tends to give a truer picture of a typical home.
- Average (mean) - Total sales divided by the number of sales. Very high or very low sales move it.
- Median - The middle price of all sales. Closer to what a typical home costs.
In most of the country, buyers pay less than the national "average", so use it as a reference point, not as your budget.
How Do Prices Compare Across Provinces And Cities?
They range from about $340,000 in New Brunswick to over $920,000 in British Columbia. Provincial and city prices give you a much better idea of what you'll pay than the national figure does.
Canada As A Whole
CREA's latest figures put the national average at $666,538 for September 2026.1
Prices In Each Province
The gap between provinces is wide. Here's each province's current price and how it moved over the past year.
| Area | Price, September 2026 | Change Over The Year |
|---|---|---|
| Canada | $666,538 | -1.6% |
| British Columbia | $923,887 | -2.4% |
| Ontario | $791,691 | -4.3% |
| Quebec | $563,241 | +2.2% |
| Alberta | $525,308 | +5.2% |
| Nova Scotia* | $423,200 | -2.5% |
| Manitoba* | $388,200 | +3.4% |
| Prince Edward Island* | $377,900 | +0.5% |
| Saskatchewan* | $376,700 | +2.8% |
| Newfoundland and Labrador* | $355,600 | +5.5% |
| New Brunswick* | $341,700 | +2.7% |
Source: CREA (September 2026).1 For the six starred provinces, the figure is the MLS HPI benchmark. For Canada and the four largest provinces, it's the average sale price. Ontario fell the most over the year. Newfoundland and Labrador and Alberta rose the most.
Average Home Prices Across Canada
Prices In Major Cities
Inside one province, prices can differ a lot from one city to the next, and big cities usually sit well above their provincial figure. Here are September 2026 MLS HPI benchmarks for Canada's major markets:
| Market | Benchmark (September 2026) | Change Since September 2025 |
|---|---|---|
| Greater Vancouver | $1,075,900 | -5.5% |
| Greater Toronto | $917,600 | -4.7% |
| Victoria | $877,000 | -0.1% |
| Ottawa | $623,500 | -0.3% |
| Montreal | $578,200 | 0.0% |
| Calgary | $569,200 | +0.2% |
| Halifax-Dartmouth | $541,700 | -4.1% |
| Quebec City | $445,800 | +4.7% |
| Saskatoon | $439,600 | +2.5% |
| St. John's | $421,800 | +6.8% |
| Edmonton | $416,700 | -0.1% |
| Winnipeg | $392,100 | +3.1% |
| Greater Moncton | $377,400 | +0.4% |
| Regina | $343,900 | +2.9% |
Source: CREA MLS Home Price Index (September 2026).1
- Most expensive - Vancouver, followed by Toronto.
- Most affordable - Regina, then Moncton and Winnipeg.
Does The Type Of Home Change The Price?
Yes, a lot. Nationally, the single-family benchmark for September 2026 was $723,500, while an apartment (condo) was $455,700.1 That's a gap of about $267,800, so the kind of home you pick can matter as much as where you buy.
| Type Of Home | Benchmark (September 2026) | 12-Month Change |
|---|---|---|
| Single-family homes | $723,500 | -3.3% |
| Townhouses | $590,700 | -4.5% |
| Condos (apartments) | $455,700 | -4.9% |
Condos usually cost less and take less work to look after, which is why first-time buyers and investors often start there. When comparing a condo with a house, set the monthly condo fees against the upkeep you'd cover yourself in a freehold home.
How Much Is A Mortgage On A $666,538 Home?
With 20% down, Canada's $666,538 average price works out to roughly $3,101 a month. At the minimum down payment, it rises to about $3,780. The table is built on a 5% fixed rate over 25 years, and the two biggest levers are your down payment and your rate.
Swipe to see all →
| Down Payment | Amount Down | CMHC Insurance Premium | Total Mortgage | Monthly Payment |
|---|---|---|---|---|
| Minimum (6.25%)* | $41,654 | $24,995 (4.00%) | $649,880 | $3,780 |
| 10% | $66,654 | $18,596 (3.10%) | $618,481 | $3,597 |
| 20% | $133,308 | None | $533,230 | $3,101 |
*The minimum on $666,538 is $41,654, or 6.25% of the price. That's 5% of the first $500,000 ($25,000), plus 10% of the $166,538 above it ($16,654).
These numbers are for illustrative purposes only. Actual numbers may vary.
Going below 20% down triggers a default insurance premium that's rolled into the mortgage. Here it would be $24,995 at the minimum, or $18,596 with 10% down. Ontario, Quebec, Manitoba and Saskatchewan also charge provincial sales tax on the premium. That tax is due up front, since it can't be borrowed, and the table leaves it out.
What Happens To The Payment When Rates Change
Borrow $533,230 after a 20% down payment, and every half point on your rate adds or trims roughly $145 to $160 monthly. Over 25 years, 6% costs about $182,000 more in interest than 4%.
| Mortgage Rate | Monthly Cost | 25-Year Interest Total |
|---|---|---|
| 4.0% | $2,805 | $308,239 |
| 4.5% | $2,951 | $352,155 |
| 5.0% | $3,101 | $397,158 |
| 5.5% | $3,255 | $443,207 |
| 6.0% | $3,412 | $490,262 |
These numbers are for illustrative purposes only. Actual numbers may vary.
Use the calculator below to test the home you're actually looking at.
Mortgage Calculator
| Amortization | Payment | Total interest | Total paid |
|---|---|---|---|
| 15 years | $3,356.62 | $164,191.53 | $604,191.53 |
| 20 years | $2,773.78 | $225,707.84 | $665,707.84 |
| 25 years | $2,435.28 | $290,584.30 | $730,584.30 |
| 30 years | $2,218.55 | $358,677.44 | $798,677.44 |
| Year | Principal paid | Interest paid | Balance left |
|---|---|---|---|
| Year 1 | $9,805.24 | $19,418.13 | $430,194.76 |
| Year 2 | $10,251.44 | $18,971.93 | $419,943.33 |
| Year 3 | $10,717.94 | $18,505.43 | $409,225.38 |
| Year 4 | $11,205.67 | $18,017.70 | $398,019.71 |
| Year 5 | $11,715.60 | $17,507.77 | $386,304.11 |
| Year 6 | $12,248.74 | $16,974.64 | $374,055.37 |
| Year 7 | $12,806.13 | $16,417.24 | $361,249.24 |
| Year 8 | $13,388.89 | $15,834.48 | $347,860.35 |
| Year 9 | $13,998.17 | $15,225.20 | $333,862.18 |
| Year 10 | $14,635.17 | $14,588.20 | $319,227.01 |
| Year 11 | $15,301.16 | $13,922.21 | $303,925.85 |
| Year 12 | $15,997.46 | $13,225.91 | $287,928.39 |
| Year 13 | $16,725.45 | $12,497.93 | $271,202.94 |
| Year 14 | $17,486.56 | $11,736.81 | $253,716.38 |
| Year 15 | $18,282.31 | $10,941.07 | $235,434.07 |
| Year 16 | $19,114.27 | $10,109.11 | $216,319.81 |
| Year 17 | $19,984.08 | $9,239.29 | $196,335.72 |
| Year 18 | $20,893.49 | $8,329.89 | $175,442.24 |
| Year 19 | $21,844.27 | $7,379.10 | $153,597.97 |
| Year 20 | $22,838.32 | $6,385.05 | $130,759.65 |
| Year 21 | $23,877.61 | $5,345.77 | $106,882.04 |
| Year 22 | $24,964.19 | $4,259.19 | $81,917.86 |
| Year 23 | $26,100.21 | $3,123.16 | $55,817.64 |
| Year 24 | $27,287.94 | $1,935.44 | $28,529.71 |
| Year 25 | $28,529.71 | $693.66 | $0.00 |
Estimates only. How we calculate: home price minus your down payment, repaid in equal payments at your rate, with interest compounded semi-annually, as fixed-rate mortgages in Canada usually are. Accelerated payments are your monthly payment split in two (bi-weekly) or four (weekly), which pays the mortgage off sooner. With less than 20% down on a home under $1.5 million, the CMHC default insurance premium (2.80% to 4.00% of the loan, by down payment) is added to the mortgage; in Ontario, Quebec and Saskatchewan, the provincial sales tax on it is due at closing and isn't included. Property tax and other fees are not included.
Which Provinces Charge Land Transfer Tax?
Most of them. You pay it, or a registration fee, when you buy, on top of your down payment. Alberta and Saskatchewan have no land transfer tax but charge a fee to register the new title. Here's what applies in each province:
| Province | What You Pay | First-Time Buyer Relief |
|---|---|---|
| British Columbia | Property transfer tax | No tax on the first $500,000 for homes worth up to $835,000 (partial relief up to $860,000) |
| Alberta | No land transfer tax. Land titles fee of $50 plus $5 for every $5,000 of value | Not applicable |
| Saskatchewan | No land transfer tax. Land titles fee charged by Information Services Corporation (ISC) | Not applicable |
| Manitoba | 0% on the first $30,000, then 0.5%, 1% and 1.5% in brackets, and 2% on the portion over $200,000 | - |
| Quebec | Municipal "welcome tax" (property transfer duties) | Refundable tax credit of up to $5,875, starting with the 2026 tax year |
| New Brunswick | 1% of the purchase price or assessed value, whichever is higher | - |
| Nova Scotia | Municipal deed transfer tax of up to 1.5% (1.5% in Halifax) | - |
| Prince Edward Island | 1% of the purchase price or assessed value, whichever is higher | Exemption for eligible first-time buyers |
| Newfoundland and Labrador | Registration fee of $100 plus $0.40 for every $100 of value over $500 | - |
Source: provincial and municipal government websites, checked October 2026. As an example, buying at the $666,538 national average in New Brunswick would mean about $6,665 in land transfer tax.
These numbers are for illustrative purposes only. Actual numbers may vary.
What Is Pushing Canadian Home Prices Up Or Down?
A few connected forces set the national average.
- Supply and demand - When buyers outnumber homes for sale, they compete, and prices climb.
- Interest rates - Higher mortgage rates raise the cost of borrowing and shrink what buyers can afford. The October 2026 rate hike is pushing variable-rate costs back up.
- Bank of Canada - It raised the policy rate on October 28, 2026, taking it from 2.25% to 2.50%.2 Pricier borrowing can cool demand, and what comes next hinges on inflation.
- The economy - Wages, jobs and inflation all shape how much Canadians can put toward a home.
Where Mortgage Rates Stand Now
After a quarter-point increase on October 28, 2026, the Bank of Canada's policy rate is 2.50%,2 and the big banks' prime rate is 4.70% (as of October 29, 2026). Variable-rate loans are getting dearer again. The big banks' posted 5-year fixed rate was 6.19% as of October 28, 2026.3 Any further moves will depend on inflation.
Where Are Canadian House Prices Heading?
Nationally, prices have cooled. The September 2026 average of $666,538 was 1.6% under a year earlier, and the national benchmark is 22.5% below its March 2022 peak.1 Still, one national number hides big regional differences.
Provinces are moving in opposite directions. Alberta (up 5.2%), Manitoba (up 3.4%) and Newfoundland and Labrador (up 5.5%) are gaining, while British Columbia (down 2.4%) and Ontario (down 4.3%) have cooled. What happens next depends on where you live, on interest rates and on buyer demand.
Should You Buy Now Or Wait?
That depends on where you are and how secure your finances are. National prices are lower than a year ago, which helps, but the October 2026 rate increase makes borrowing cost more. Prices are falling in places like Ontario and B.C. and rising in Alberta, Quebec and parts of Atlantic Canada. If your income is steady and you plan to stay put for years, a softer local market can work in your favour. If you go ahead, knowing how to shop for a mortgage helps you get a better rate.
Is It Better To Rent Or Buy In Canada?
Buying usually costs more at the start, but you build equity as you pay down the mortgage. The right choice depends on your budget and how long you plan to stay.
Owning Vs. Renting: The Costs Side By Side
Here's how the main costs compare.
| Factor | Cost To Own | Cost To Rent |
|---|---|---|
| Upfront costs | Higher. You need a down payment, often 5% to 20% of the price, plus closing fees, legal costs and land transfer taxes. | Usually just a deposit and the first month's rent. |
| Monthly expenses | Your mortgage, plus property taxes, insurance and maintenance. | Rent is predictable, and repairs and property taxes aren't your problem. |
| Equity building | Every payment adds to the share of the home you own. | Rent doesn't build ownership. |
If you plan to stay a long time and can cover the upfront costs, buying usually comes out ahead.
How Do You Find Out What Your Home Is Worth?
Averages won't tell you what your own home is worth. That depends on its location, size and condition, and on what similar homes nearby sold for recently. For an exact number, order a professional appraisal, or get an estimate with a tool like how much is my house worth.
Your home's value is the first step to working out your home equity, the part of the home you actually own. Subtract what's left on your mortgage from the value, and the rest is your equity. From there, you can plan how to grow it.
Who Feels High Home Prices The Most?
High prices shape who can buy, and where.
- First-time buyers - Getting in is hardest in Vancouver and Toronto, where prices sit far above the national level.
- Buyers in cheaper regions - Atlantic Canada and the Prairies remain more affordable, so owning a home there is within reach for more people than in Ontario or B.C.
What Limits How Much You Can Spend On A Home?
A few rules and costs decide how much you can realistically spend.
- Down payment rules - You need at least 5% down on a home priced at $500,000 or less, and more on pricier homes. With less than 20% down, you also pay a mortgage insurance premium.
- The stress test - You have to show you could keep up with payments at a qualifying rate above your actual rate. It's meant to make sure you can cope if rates or debts go up.
- Closing and ongoing costs - On top of the price, budget for legal fees, land transfer tax and an inspection, then property taxes and maintenance once you move in.
Why Lenders Require Default Insurance Below 20% Down
A mortgage with less than 20% down is called high-ratio, and in Canada it must carry default mortgage insurance. The insurance protects the lender if the borrower stops paying.
How Much Of Your Budget Should Go To A Home?
Weigh your income and debts against your long-term goals. These guidelines help you land on a price that won't leave you stretched. In the end, your mortgage affordability rests on your income, debts and down payment.
- Debt ratios - Lenders use your Gross Debt Service (GDS) and Total Debt Service (TDS) ratios. GDS looks only at housing costs as a share of gross income. TDS adds in every other debt.
- Down payment - At $500,000 or less, the minimum is 5%. Above that, you need more.
A mortgage calculator gives you a quick estimate of what fits your budget.

Putting The National Average To Work
At $666,538 in September 2026, the national average is only a rough guide. Vancouver and Toronto remain the priciest cities, and the Prairies and Atlantic provinces the most affordable. Look past the price tag to the full cost of owning, including your mortgage payment, taxes and maintenance. Set a budget you can live with, borrow less than your maximum, and leave room for rates to change.
Average House Price In Canada FAQs
Why do home prices vary so much between provinces?
What is the most expensive city in Canada for housing?
Where in Canada are homes cheapest?
Is the median home price more useful than the average?
Will Canadian home prices go up or down?
How much have Canadian home prices fallen in the last year?
What's the mortgage payment on an average Canadian home?
Is there land transfer tax in every province?
Sources
- Canadian Real Estate Association (CREA). (2026). Housing market statistics and MLS Home Price Index, national and provincial (September 2026). https://www.crea.ca/housing-market-stats/
- Bank of Canada. (2026). Bank of Canada raises the policy rate by 25 basis points to 2.5%. https://www.bankofcanada.ca/2026/10/fad-press-release-2026-10-28/
- Bank of Canada. (2026). Posted interest rates offered by chartered banks (weekly, October 28, 2026). https://www.bankofcanada.ca/rates/banking-and-financial-statistics/posted-interest-rates-offered-by-chartered-banks/
Note: Loans Canada does not arrange, underwrite or broker mortgages. We are a simple referral service.